Helvetica Group · $300K–$10M+

    Commercial Real Estate
    Bridge Loans

    Purchase a property, refinance a maturing loan, fund lease-up or close a 1031 exchange. Helvetica provides bridge financing from $300,000 to $10 million and up, with rates starting at 8.99% and up to 65% loan-to-value. Bank turndowns and low-occupancy properties are considered based on collateral and exit strategy.

    $1B+
    Transactions Closed
    $300K
    Minimum Loan Size
    $10M+
    Loan Size (Larger Case-by-Case)
    25+
    Years Direct Lending

    The Short Answer

    What is a commercial real estate bridge loan?

    A commercial real estate bridge loan is short-term financing secured by the property. It covers the gap until a bank refinance, a lease-up or a sale repays it. We size ours to the property's current value and the repayment plan, from $300,000 to $10,000,000+ at up to 65% loan-to-value. Here is how that worked on a Tucson industrial bridge loan we funded.

    01
    The Gap
    A 10-year bank loan came due four months after a tenant leasing 51% of the building moved out. At 49% occupancy, a bank refinance was off the table.
    02
    The Bridge Loan
    We funded a $1,450,000 first-mortgage bridge loan, 12 months interest-only, at 60.42% of the property's value.
    03
    The Exit
    The owner re-leases the empty space, then refinances with a bank, and that permanent loan repays the bridge loan.

    Loan Parameters

    Bridge loan rates, terms and loan sizes.

    Terms run from 6 months to 5 years or more, with fixed and interest-only options. Availability depends on the property, location, licensing and underwriting.

    Loan Size
    $300K–$10M+
    Per transaction
    Loan-to-Value
    Up to 65%
    As-is value; exceptions possible based on underwriting
    Term
    6 mo.–5 yr+
    Fixed and interest-only options
    Rates
    From 8.99%
    Based on LTV, asset type, term
    Discount Points
    1.5% +
    Based on complexity and timeline
    Close Time
    3–10 days
    Typical, following receipt of all requested documentation
    Occupancy
    0–100%
    Stabilized and distressed accepted
    Geography
    Nationwide
    Metro areas nationwide, selectively. Headquartered in Carlsbad near San Diego. See San Diego bridge loans

    Bridge Loan Case Studies

    Bridge loans, recently closed.

    A $2.5 million construction-loan refinance, a $2.34 million bridge to sale, a $2 million rental-portfolio refinance and a $1.45 million lease-up bridge.
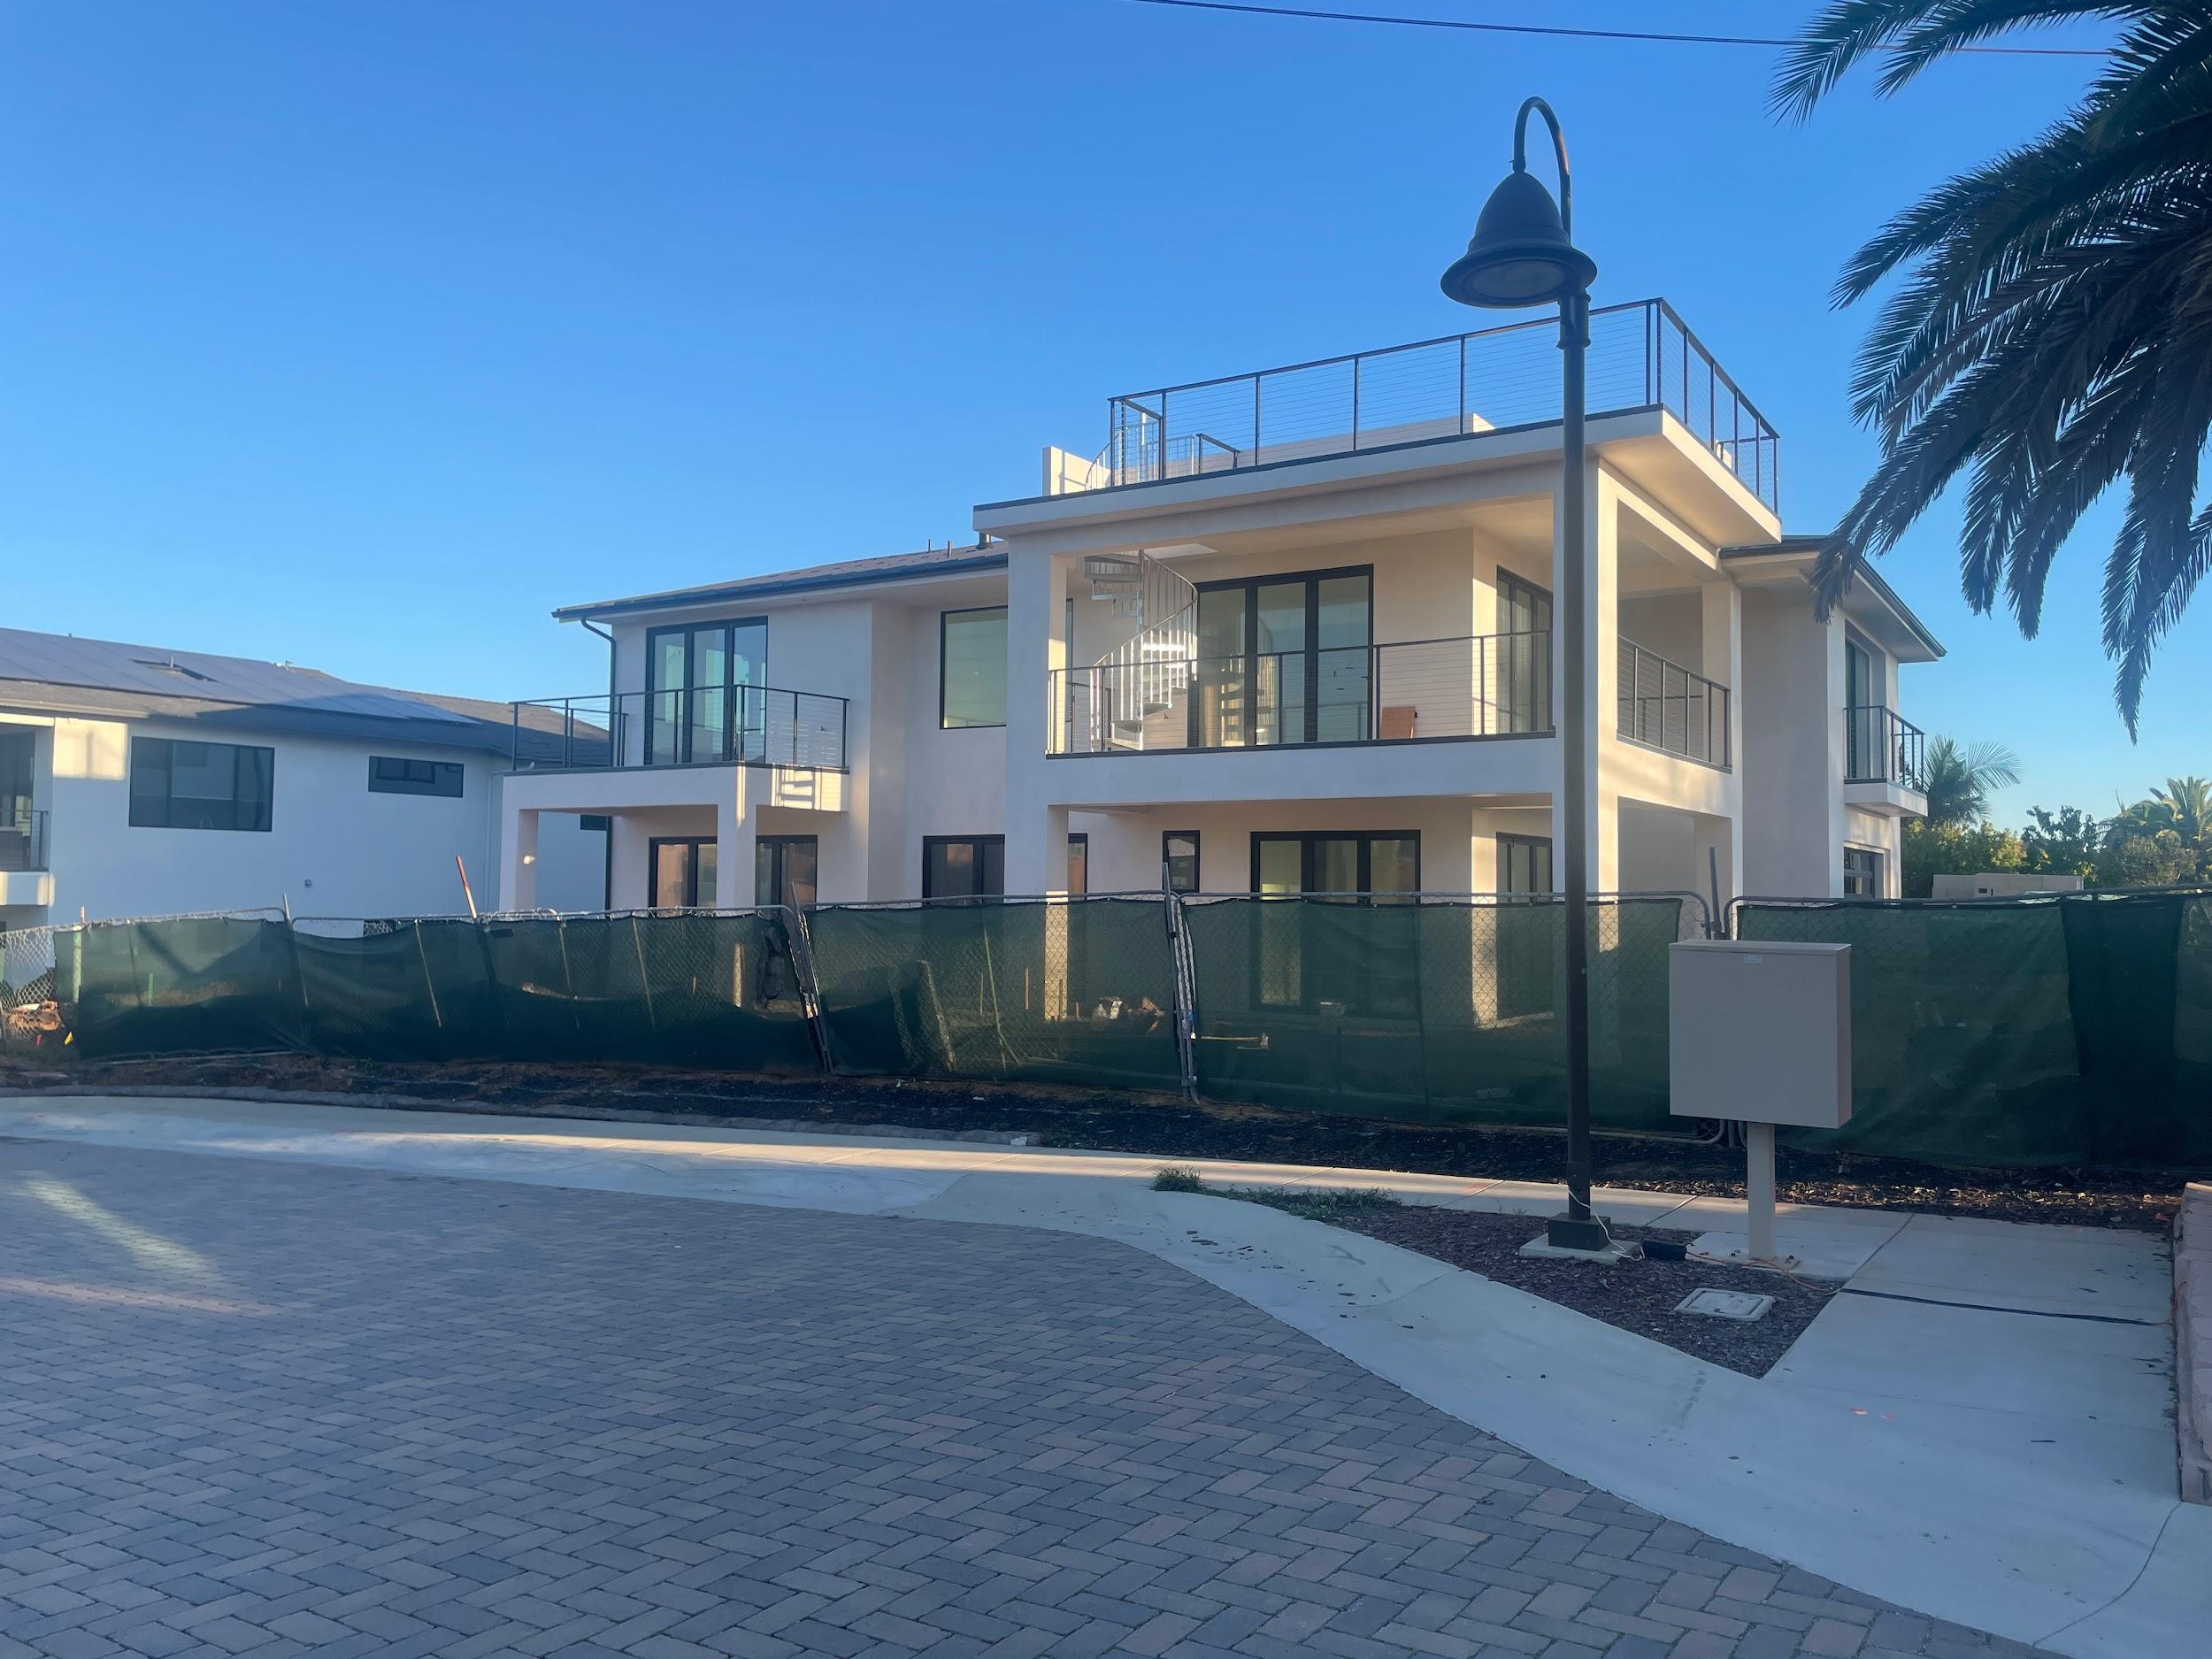
    Completed new-construction ocean view residence in Carlsbad, California
    $2,500,000
    Bridge · Construction Takeout
    New Ocean View Residence
    Carlsbad, CA
    A completed coastal home was refinanced out of a maturing $2.1 million construction loan at 47% loan-to-value, with $300,000 of business-purpose cash out. A 12-month interest-only term let the owner market the home on his own schedule.
    ↳ Maturing construction loan · Vacant collateral · No income documentation
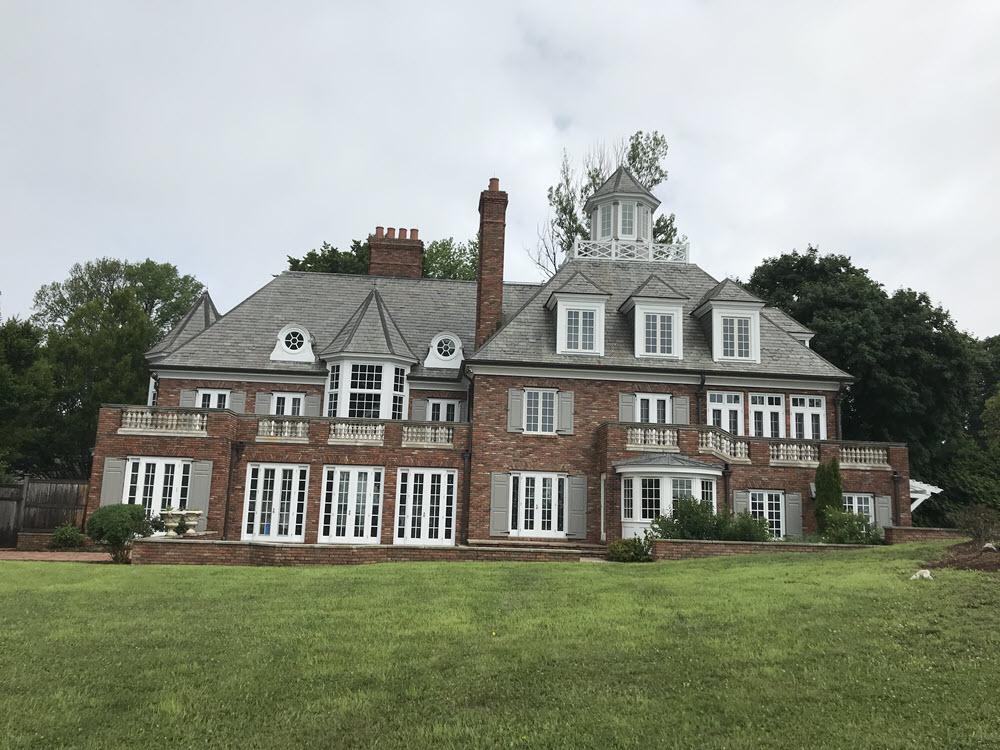
    Renovated coastal residence listed for sale in Norwalk, Connecticut
    $2,340,000
    Bridge · Matured Loan
    Renovated 9,608 SF Residence
    Norwalk, CT
    A defaulted $1.67 million purchase loan was coming due while the home sat on the market. Helvetica advanced a first-mortgage bridge with an 18-month interest-only term and an interest reserve at 55% loan-to-value.
    ↳ Defaulted loan · Credit challenged · Bridge to sale
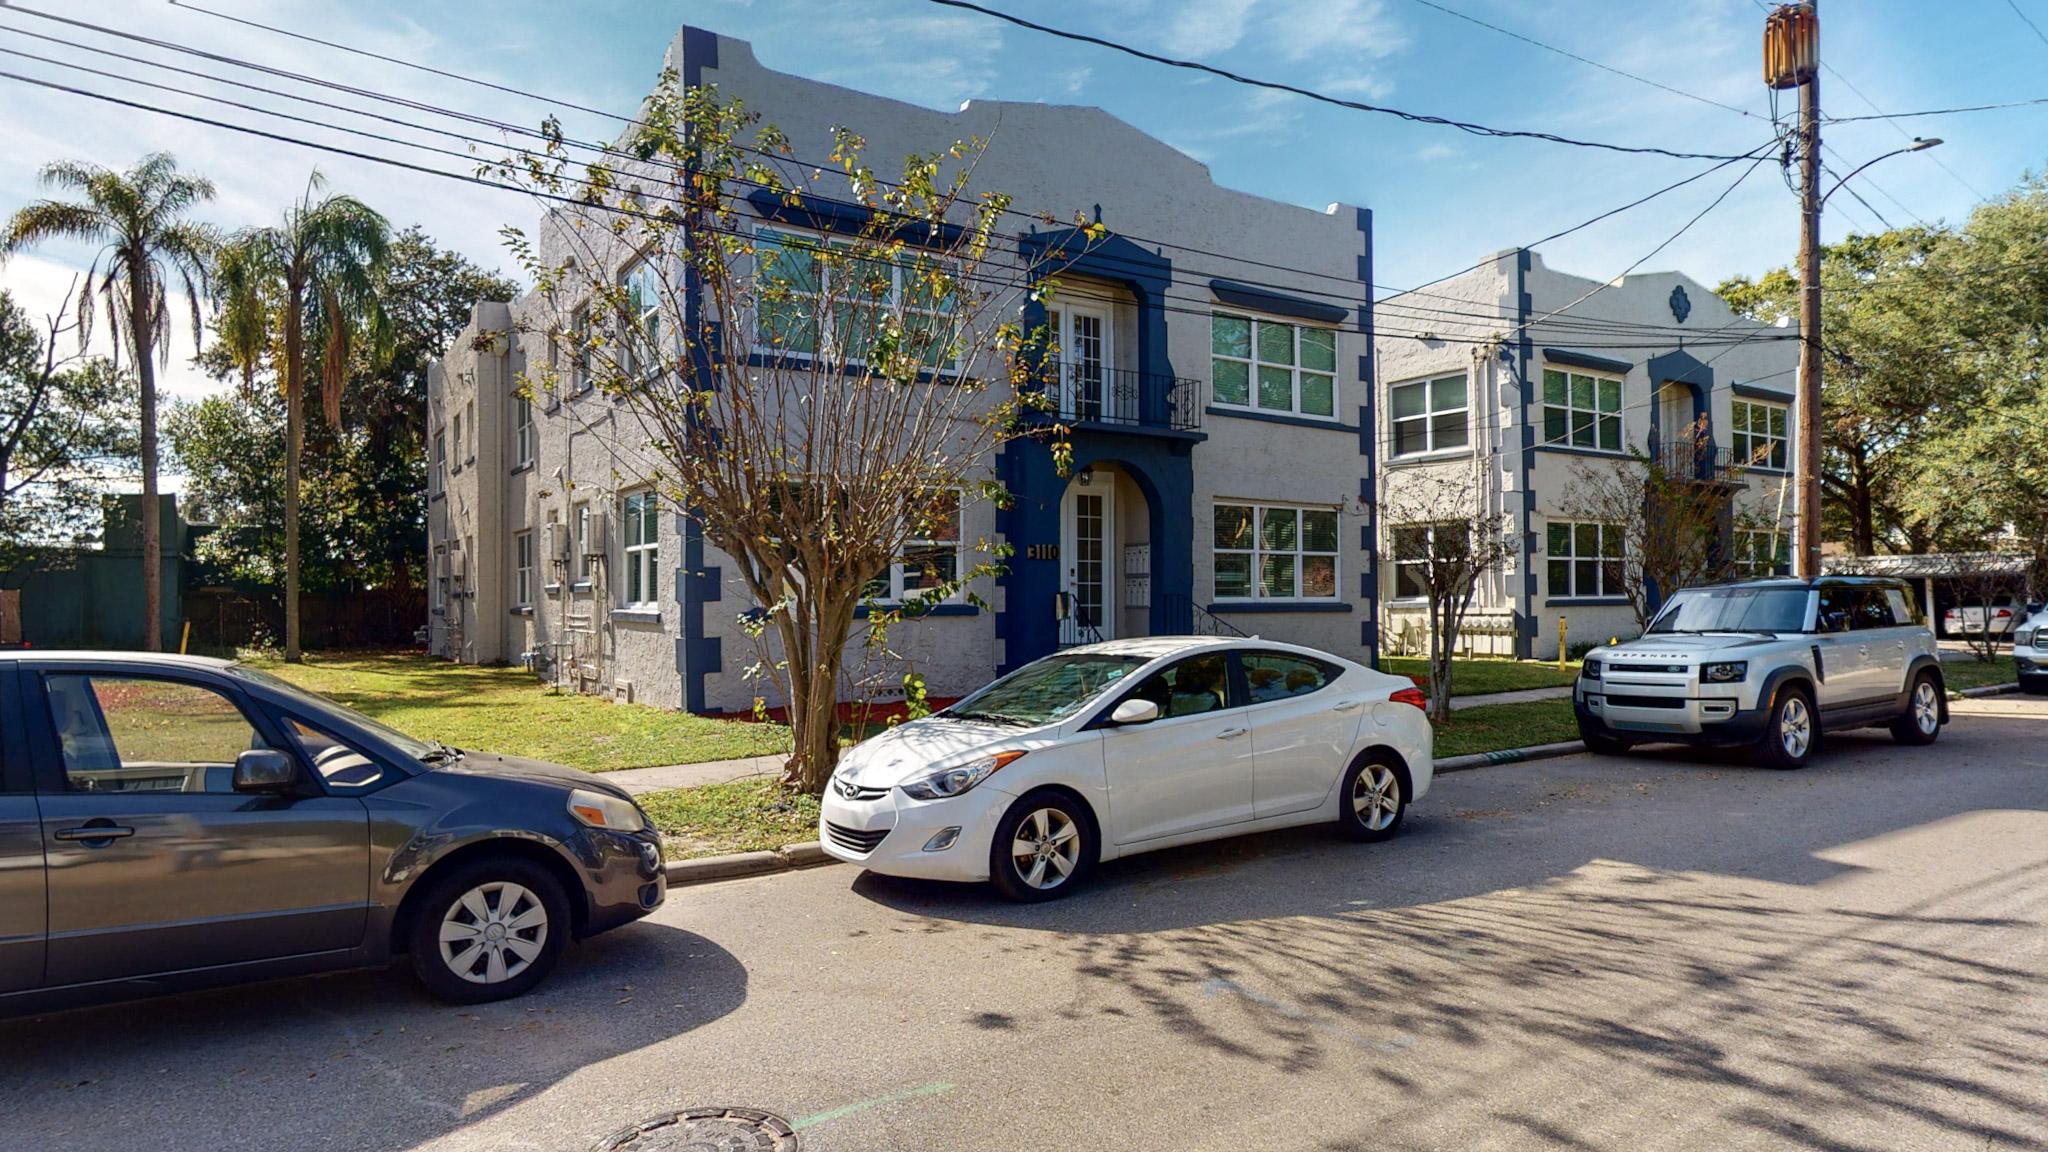
    Waterfront multifamily rental buildings in Tampa, Florida
    $2,000,000
    Bridge · Multifamily
    Four-Property Rental Portfolio, 29 Units
    Tampa, FL
    Four rental loans matured while the owner was mid-refinance. Helvetica funded a 12-month interest-only bridge secured by first mortgages on 29 units across four properties, at 45.3% of their $4,417,000 combined value.
    ↳ Four maturing loans · Cross-collateralized · Bridge to takeout
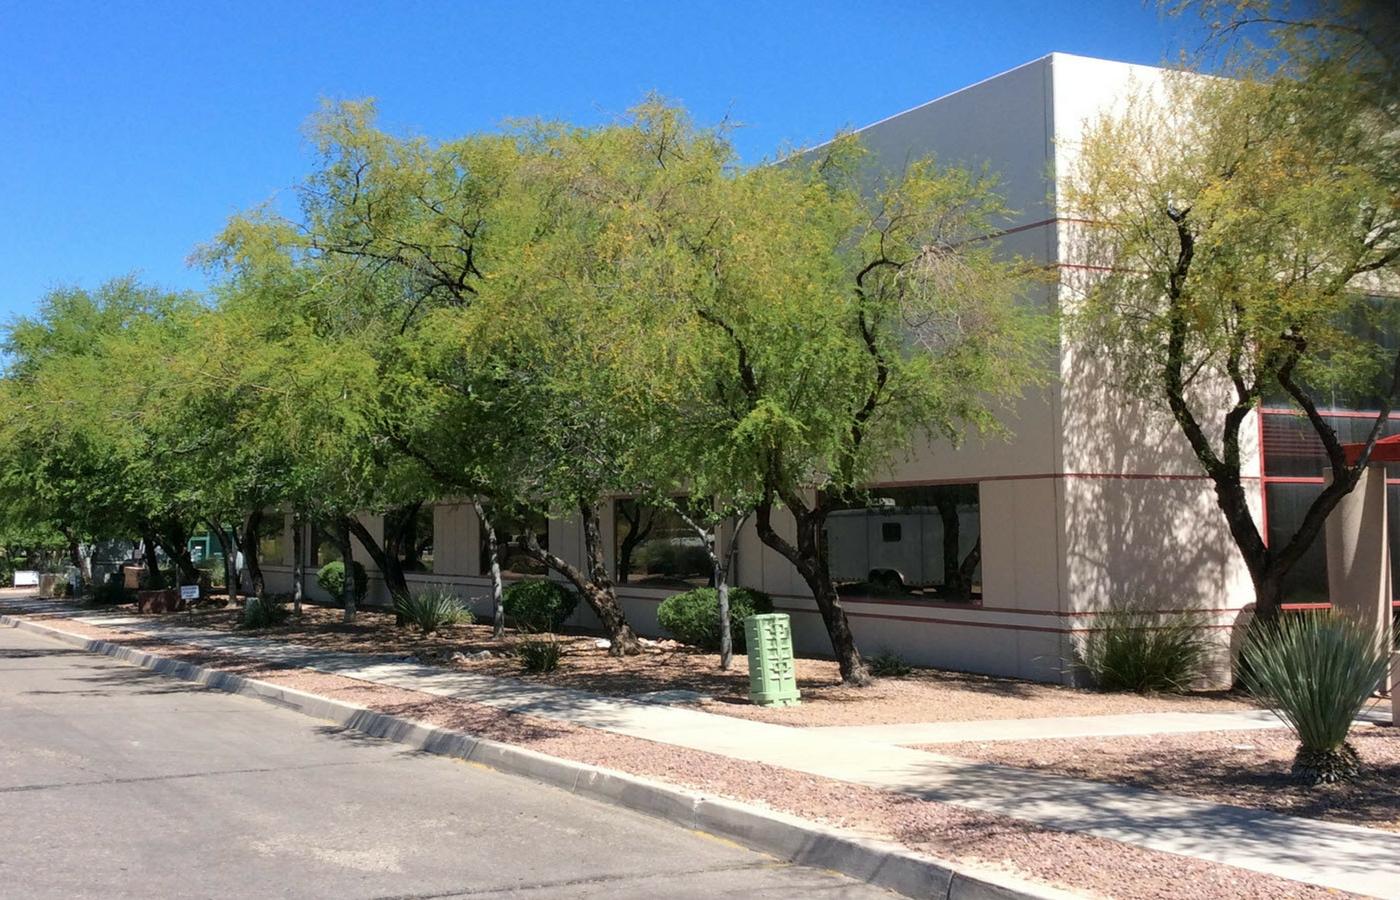
    Multi-tenant light industrial building in Tucson, Arizona
    $1,450,000
    Bridge · Low Occupancy
    Multi-Tenant Light Industrial
    Tucson, AZ
    A 10-year bank loan came due four months after a tenant leasing 51% of the building moved out. Helvetica funded a 12-month bridge at 60.42% loan-to-value so the owner could re-lease and return to a bank for permanent financing.
    ↳ Bank turndown · Tenant vacancy · Lease-up bridge

    When to Call Helvetica

    Purchase, refinance, lease-up and 1031 exchange financing.

    A bridge loan provides time to sell, stabilize a property or secure permanent financing. We review current collateral value and how the loan will be repaid.

    Bank Turndowns
    A bank decline does not automatically rule out a bridge loan. We review property value, requested leverage and the repayment plan, including stated-income and alternative-documentation scenarios.
    Time-Critical Closings
    Acquisition financing when a seller's deadline arrives before bank financing is ready. Typical closings take 3–10 days following receipt of all requested documentation; timing depends on the deal.
    Unstabilized & Value-Add
    Bridge financing for low occupancy, tenant vacancy and repositioning. Underwriting starts with current property value and considers the lease-up or stabilization plan before a permanent refinance or sale.
    1031 Exchange Bridge
    Purchase bridge financing when replacement-property timing and permanent financing do not align. Discuss 1031 exchange bridge loans, or see how reverse 1031 exchange bridge loans let you buy before you sell.
    NNN Bridge Loans
    Purchase, refinance or reposition single-tenant and multi-tenant net-leased retail, restaurant and industrial property. Discuss NNN bridge loans, including sale-leaseback and portfolio scenarios.
    Foreclosure Bailouts
    Notice of default filed, cure deadline approaching. We move before the trustee sale. Asset-based underwriting means we can act fast.
    Partner & Estate Buyouts
    Equity event with a tight timeline and no bank appetite. We've funded buyouts where the asset is solid but the situation is complicated.
    Maturing Loan & Cash-Out Refinance
    Refinance a coming-due purchase or construction loan while preparing for a sale or permanent takeout. Cash-out requests are evaluated against collateral value and the proposed use of funds.
    REO Acquisitions
    Distressed REO purchase where the property can't qualify for conventional financing yet. We fund the acquisition, you execute the plan.

    Collateral Types

    Retail, NNN, office, industrial and mixed-use bridge loans.

    Bridge financing for retail centers, triple net (NNN) properties, offices, industrial buildings, multifamily and investment residences. See our dedicated NNN bridge loan page, NNN retail bridge loans funded in Chula Vista, Los Banos and on a three-property NNN retail refinance in Columbus, or review the lending guidelines.

    Retail Strip & Centers
    Multifamily (5+ units)
    Mixed-Use
    Office Buildings
    Industrial & Warehouse
    Self-Storage
    Single-Family Investment
    Churches
    Hospitality
    Mobile Home Parks
    RV Parks
    Special Purpose

    How It Works

    From submission to funding.

    Start with MILA / Loan Desk at (760) 624-3301, available 24x7, or submit the deal details for review.

    01
    Submit the Deal
    Send us the executive summary: property address, loan amount, LTV, borrower background, and your exit strategy. One page is enough to start.
    02
    Initial Review
    The lending team reviews the property, requested amount, current value and exit strategy, then asks for any information needed to evaluate the loan.
    03
    Term Sheet Issued
    If the proposed structure fits, we issue a term sheet and begin underwriting. Final approval depends on documentation, property review and closing requirements.
    04
    Close & Fund
    Our closing team coordinates with your counsel and title company. Typical closings take 3–10 days after all requested documentation is received, depending on transaction complexity.

    Common Questions

    Straight answers.

    The questions brokers and borrowers ask before they submit a loan.

    What is a commercial bridge loan?
    A bridge loan is short-term financing — terms from 6 months to 5+ years — that provides capital while a borrower works toward a longer-term solution: a permanent refinance, stabilization, or sale. Bridge loans are asset-based, meaning the underwriting focuses on the property's current value and the borrower's exit plan rather than a standard income or credit profile.
    Do you lend on bank turndowns?
    Yes — frequently. A bank turndown tells us the deal has complexity, not necessarily that it's a bad loan. We underwrite to the collateral and exit strategy. If the asset supports the loan and the exit makes sense, the fact that a bank declined is not disqualifying.
    What loan-to-value will you lend to?
    Up to 65% of as-is value; exceptions possible based on underwriting. For distressed, vacant, or value-add properties, we underwrite to current market value with consideration for the repositioning plan. We do not lend to ARV (after-repair value) without significant demonstrated basis and a credible execution plan.
    How fast can you close?
    It depends on borrower preparedness, third-party reports and complexity; we typically close in 3–10 days following receipt of all requested documentation. We close what we commit to; we do not issue soft letters of interest and fade at the finish line.
    Do you lend in states outside California?
    Yes, selectively. We lend in metro areas nationwide, selectively; availability varies by deal, property type, licensing and underwriting. Contact us with your deal and geography and we'll give you a straight answer.
    Do you work with mortgage brokers?
    Brokers are our primary sourcing channel. We protect broker relationships and pay competitive referral commissions. A broker approval is required prior to loan funding on broker-originated transactions. Visit our broker program page or submit a loan directly to get started.
    How do you qualify for a commercial bridge loan?
    We underwrite the property and the exit, not a bank credit matrix. The loan must be for business purposes on commercial or investment real estate, from $300,000 to $10,000,000+, at up to 65% of as-is value (exceptions possible based on underwriting). Send the property, loan amount and exit strategy, and we respond with an indication or a specific question.
    Is it hard to get a commercial bridge loan?
    It is usually easier than a bank loan when the collateral is solid. Bank turndowns, low occupancy and tight deadlines are common in our files. What matters most is equity in the property and a believable way to repay, such as a sale, a refinance or stabilization.
    What is the downside of a bridge loan?
    A bridge loan costs more than a long-term bank loan and runs for a shorter term, so it works best with a clear plan to repay. Our rates start at 8.99% with discount points of 1.5% +, and terms run from 6 months to 5+ years. Borrowers use that time to stabilize, sell or refinance.
    How much does a commercial bridge loan cost?
    Rates start at 8.99% and discount points are 1.5% +, priced on loan-to-value, property type, term and complexity. Interest-only and fixed options are available. A $350,000 loan, for example, falls inside our $300,000 to $10,000,000+ range and is priced on those same factors.
    Are bridge loans the same as hard money loans?
    They overlap. Both are short-term, asset-based loans from private lenders. A commercial bridge loan is built around a defined exit on commercial or investment property, with terms from 6 months to 5+ years and up to 65% LTV. Helvetica is a direct lender, so the people who review the deal are the ones who fund it.
    Can I get a commercial bridge loan in California?
    Yes. Helvetica Group is based in Carlsbad, at 5927 Balfour Ct., Suite 208, and funds commercial bridge loans across California. We also lend in metro areas nationwide, selectively. Call MILA, our AI loan assistant, 24/7 at (760) 624-3301, or submit a loan to start.

    Discuss your bridge loan.

    Call MILA / Loan Desk first, available 24x7 at (760) 624-3301. For a loan review, submit the property address, requested amount, estimated value, closing deadline and repayment plan.

    BROKER SUBMISSIONS WELCOME · CA DRE #01366104 · CFL #603E072
    Who you work with

    Your loan is reviewed and decided by our own lending team in Carlsbad, not passed to a third party.

    Chad Mestler

    Chad Mestler

    Chief Executive Officer

    25+ years in commercial real estate investing, lending and structured finance.

    Tom Phanco

    Tom Phanco

    Managing Director

    Oversees origination and wholesale lending.

    MILA, Helvetica Group's AI loan assistant

    MILA

    AI Loan Assistant

    Takes loan inquiries 24/7, by phone or chat.

    (760) 624-3301